


Autonomous mobility is projected to generate up to $30bn in economic value across the GCC by 2040, driven by a structural shift from government-funded pilot programmes to commercial deployment models.
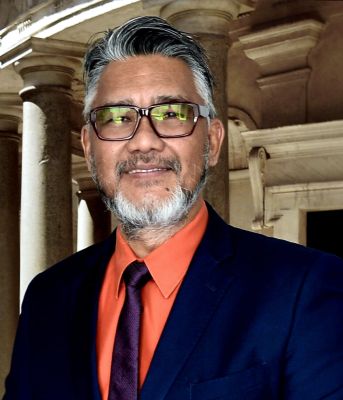
Speaking at the Smart Mobility Summit during MWC Doha 2026 Monday, Strategy& Middle East partner Mark Haddad noted that commercial deployment requires moving past early government-led trial phases.
“Historically, these pilots were all government-led, and rightly so, because the private sector needed government backing. Today, however, three business models are emerging,” Haddad explained.
Haddad highlighted three distinct commercial models operating globally: operator-led, technology-led, and partnership-led frameworks.
Under the operator-led framework, Haddad said mobility companies purchase vehicles and manage operations directly, such as Uber deploying 20,000 Lucid electric vehicles in the US.
“The operator purchases the vehicles, runs the service, and keeps the fares. Uber in the US is the clearest example: that’s the rationale behind its plan to deploy 20,000 Lucid cars over the next season and transport passengers through its fleet of partners,” he pointed out.
In technology-led structures, autonomous technology developers own and operate the fleets themselves, said Haddad, citing Waymo’s driverless operations in San Francisco.
The partnership-led model shares operational and regulatory responsibilities between public entities and private companies, making it particularly suitable for the Middle East, according to Haddad.
“The third emerging model, which is particularly well suited to our region, is what we call the partnership debt model. Under this approach, the government and private sector share the burden,” he explained.
Under this framework, municipal authorities issue permits and guarantee baseline demand, while private partners manage fleet operations and share top-line revenue, Haddad said.
He said, “The government secures permits and guarantees a minimum level of demand, for example, by procuring a minimum number of cars and subsidising them, while private operators run the fleet and retain a share of the revenue.”
According to Haddad, Abu Dhabi has implemented this hybrid approach by combining government licensing with WeRide’s self-driving systems and Uber’s dispatch network.
By 2040, mobility operators are projected to capture $21bn of the regional market value, up from $1.2bn in 2030, noted Haddad.
He said telecommunications operators are forecast to capture $3bn by 2040, compared to $75mn in 2030, by delivering digital network infrastructure and connectivity services.
Haddad underlined that Transport authorities are projected to collect $2bn in licensing revenues by 2040, rising from $75mn in 2030.
He stated that scaling autonomous mobility requires four critical advancements in artificial intelligence capabilities. These developments include driving reliably in diverse weather conditions such as heavy rain and dust, alongside large-scale simulation testing.
AI systems must also evolve to manage multi-agent fleets of thousands of vehicles and achieve full interoperability with urban traffic control infrastructure, Haddad said, adding that the GCC possesses the regulatory backing, capital commitment, and digital infrastructure required to lead commercial fleet integration over the coming decade.

