


Hawkish European Central Bank (ECB) officials aim to start unwinding the institution’s €5.1tn ($4.9tn) asset hoard by early 2023 while retaining interest rates as their primary monetary-policy tool, according to people familiar with the matter.
A consensus is emerging among some Governing Council members that the process of shrinking the balance should run in the background while the ECB focuses on setting borrowing costs, they said, declining to be identified because discussions on the matter are private.
That would require a decision on a framework that could then be revisited after a period of time, the people said. The officials favour letting bonds mature rather than resorting to debt sales, though that option shouldn’t be entirely excluded. They could also envisage keeping up some reinvestments to moderate the pace of unwinding.
An ECB spokesperson declined to comment on plans to unwind the balance sheet.
ECB hawks have effectively dictated the momentum of monetary policy since early June, a dominance over decision-making that suggests their opinions might well continue to hold sway.
Officials started discussions on a possible strategy for so-called quantitative tightening last week at a meeting in Cyprus, Luxembourg central bank chief Gaston Reinesch said in a blog post on Wednesday.
How to begin offloading bonds bought up over several years of stimulus is a highly sensitive matter for the ECB. Its monetary policy has struggled to stay focused against the distraction of how more restrictive measures might hurt Italy’s debt sustainability.
A blowout in that country’s bond yields in June forced officials to devise a new crisis tool to ensure that they could continue raising interest rates without harming the integrity of the euro region. The Bank of England’s own confrontation with financial-market turmoil in recent weeks similarly illustrates the dangers of how a plan to reduce bond holdings can go awry. Dutch Governor Klaas Knot told Bloomberg Television on Wednesday about how the ECB would want to do things differently from the British central bank. “They actively have to sell” because of their long-dated portfolio, he said. “Like in the US, we have bonds over the full maturity, and we think we can do QT by just rolling off existing bonds by less than full reinvestment, which is naturally a smoother process.”
ECB officials are agreed that they shouldn’t start shrinking the balance sheet until they reach a level of rates deemed to be neutral - neither stimulating nor constricting the economy. It’s likely that they might do that as soon as December.
Slovak central bank chief Peter Kazimir insisted that the Governing Council makers won’t rush to sell off securities.
“Quantitative tightening is an inevitable part of normalisation and policy tightening but it will not start this year,” he told Reuters in an interview.
The opportune time to begin winding the balance sheet down will be March 2023, according to David Powell at Bloomberg Economics, who predicts an average reduction of €29bn a month, or just under 1% of the size of the combined portfolios of quantitative easing and pandemic emergency bond purchases.
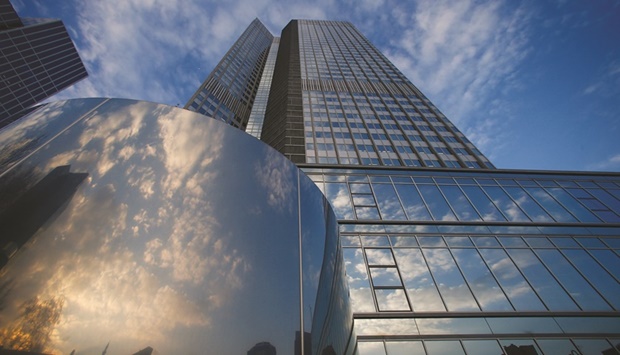
The headquarters of the European Central Bank in Frankfurt. Hawkish ECB officials aim to start unwinding the institution’s $4.9tn asset hoard by early 2023 while retaining interest rates as their primary monetary-policy tool.