


After a quiet few weeks, the yuan is centre stage again. The currency slid towards its weakest in a decade on Friday, approaching a key support level of 7 per dollar before managing a slight rebound.
The moves came after it fluctuated in a narrow band of about 1% through October, the tightest range since April 2017. Now bearish wagers are building again as capital outflow pressure grows.
“A further depreciation of the yuan relative to the dollar would soften the blow of US tariffs but at the considerable risk of triggering substantial capital outflows,” said Eswar Prasad, former IMF China division chief and author of “Gaining Currency: The Rise of the Renminbi.”
The yuan has tumbled 9% against the dollar in the past six months, dragged down by trade tension with the US and bets of further monetary easing by the People’s Bank of China.
The drop has stoked debate over when or whether officials might intervene to prevent it sliding past the milestone of 7 against the dollar – a level not reached since the global financial crisis.
There are signs China is already growing uncomfortable with the weakness. At a briefing in Beijing on Friday, PBoC Deputy Governor Pan Gongsheng said the central bank will take macro-prudential measures to stabilise expectations in the foreign-exchange market, and that it is confident the yuan will be kept basically stable at reasonable levels.
Here are the reasons that show mounting depreciation pressure on the yuan:
The yuan’s initial weakness on Friday came as the PBoC cut its daily reference rate beyond 6.95 per dollar to a 21-month low – a sign that the central bank is in no rush to stem the depreciation. The yuan is also near the lowest level on record against a basket of currencies.
The offshore yuan’s three-month risk reversal, a gauge reflecting traders’ bearishness on the currency in the options market, on Friday surged to the highest level since January 2017. That suggests demand for wagers betting on further depreciation is climbing.
Chinese banks last month sold the most foreign-exchange to clients since December 2016, according to data released on Thursday by the currency regulator. The figures came after the central bank reported the biggest drop in positions for foreign-exchange purchases since January 2017, reflecting greater intervention.
The notional value of new options betting the yuan will weaken past 7 per dollar has risen to $62bn so far this month, triple the level seen in September, according to Bloomberg calculations based on data from Depository Trust & Clearing Corp.
Options prices show the chances of the yuan hitting 7 next quarter nearly doubled in the past three months to 43% on Friday.
The yield spread between China and US 10-year government bonds narrowed to 37 basis points last week, the lowest since April 2011. That makes yuan-denominated assets – such as onshore bonds – less attractive, and thus reduces capital inflows.
“If there is market pressure for the currency to go beyond 7, they will probably allow it to happen,” Joachim Fels, global economic adviser at Pacific Investment Management Co, said in an interview in Hong Kong. “There is still the risk of accelerated capital outflows, which is why the central bank wants to at least smooth the currency depreciation.”
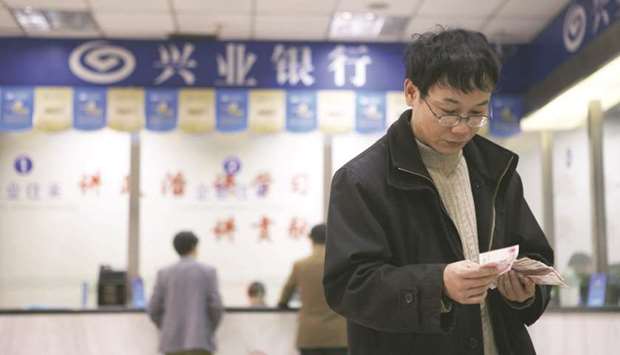
A customer counts his yuan notes at a branch of Industrial Bank in Shanghai (file). The yuan has tumbled 9% against the dollar in the past six months, dragged down by trade tension with the US and bets of further monetary easing by the People’s Bank of China.