


Capital Intelligence (CI), a global credit rating agency, has affirmed Qatar Islamic Bank’s (QIB) financial strength rating (FSR) at ‘A’ with a “stable” outlook.
The FSR is supported by good overall capital adequacy including a strong and improved CET-1 (common equity Tier-1) ratio and still fairly good profitability, which is underpinned by a low cost base, CI said.
QIB’s position as the leading Islamic bank in Qatar is also a supporting factor, given the demonstrated preference amongst Qataris for personal banking on a Shariah-compliant basis.
Although the main constraint to the rating is the liquidity, which tightened in 2015 and 2016, with particular concern on the now very tight net liquid asset ratio, CI said it was mitigated by QIB’s liquidity coverage ratio, which is well in excess of current and future regulatory needs and a good net stable funding ratio.
“A slower pace of asset growth in 2017 coupled with funds raised through probable longer tenor capital markets transactions should hopefully translate into a better liquidity position,” it said, referring to the recent annual general assembly meeting that saw shareholders’ nod to enhance the perpetual sukuk issuance level from QR5bn to QR7.5bn.
With the amount of such sukuk already issued standing at QR4bn, there is now “considerable room” for a further issue, possibly this year, it said.
With other financial metrics generally sound – and in several cases very sound – the other present constraints are the very significant concentrations in financing by sector and obligor, in depositors, and in the uncertainties around gross domestic product (GDP) growth and therefore the likely trajectory of credit growth, CI said.
The lender’s long-term foreign currency rating (FCR) has been upgraded to ‘A+’ while the short-term FCR is affirmed at ‘A2’ on a ‘stable’ outlook.
“We are very pleased with the upgrade of our long-term FCR and the affirmation of our FSR by CI. They are solid confirmations asserting the bank’s enhanced asset quality and robust capital position.” Bassel Gamal, QIB group chief executive said.
Reflecting QIB’s generally strong financial profile and stronger capital adequacy, following the 2016 perpetual sukuk issue, these ratings are supported by the robust growth potential of the economy and ongoing sovereign support for Qatari banks.
Finding that the Qatari government has demonstrated strong support for individual banks as well as the system as a whole, which mitigates the now rather tight liquidity ratios at most individual banks, it said based on this, the support rating is affirmed at ‘2’.
Despite lower hydrocarbon prices and its effect on the budget, Qatar’s real GDP growth is slated to continue, albeit at a slower pace, CI said, adding economic conditions are likely to remain better than those in most other Gulf countries, although there are signs of oversupply in the realty sector.
QIB expects credit to grow, but at a rather slower pace than was seen in the high growth 2014-15 period – perhaps 9% or less. Growth in the asset base and in profit at the operating level is likely to closely track the growth rate of the financing book, although the performance at the net level (absent recoveries) is likely to be impacted by a continuing high cost of credit, it said.
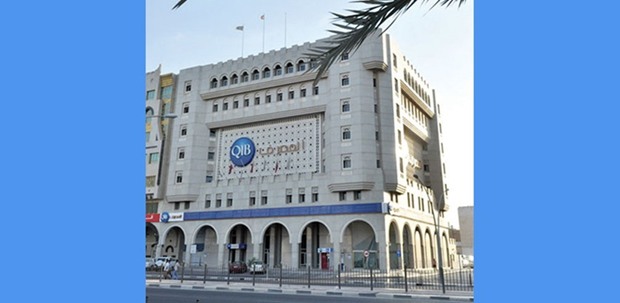
QIB’s position as the leading Islamic bank in Qatar is supported by the demonstrated preference among Qataris for Shariah-compliant personal banking