


Qatar Re, a Bermuda-registered reinsurance arm of Qatar Insurance Company (QIC), has successfully placed $450mn perpetual Tier 2 notes, which was oversubscribed 14 times owing to the overwhelming response mainly from investors in Asia, the UK, the Middle East and Continental Europe.
The $450mn ‘Reg. S Perpetual non-call 5.5 subordinated Tier 2’ notes were the debut issuance in the international capital markets from Qatar Re, which is licensed as a Class 4 reinsurer by the Bermuda Monetary Authority.
“Interest from investors was outstanding following an extensive roadshow. This new $450mn issue reinforces our efficient capital structure that offers excellent security to policyholders and positions us well for the next phase of growth,” according to Khalifa Abdulla Turki al-Subaey, QIC Group president and chief executive.
The issue attracted over 290 orders for more than $6.5bn, said Qatar Re, a global multiline reinsurer writing all major property and casualty as well as speciality lines of business.
The reinsurance entity said it achieved a very “balanced” international distribution with 30% of the orders from Asia, 29% from the UK, 20% from the Middle East, 19% from the Continental Europe and 2% from other regions.
The initial coupon has been set at 4.95% per annum. It will be fixed until the first call date in September 2022 and reset to five-year ‘MS plus the initial margin’, and every five years thereafter.
The notes would be treated as Tier 2 capital from a regulatory perspective in both Bermuda for Qatar Re and Qatar for QIC. Additionally, the notes, rated BBB+ by Standard & Poor’s, have been structured to meet the credit rating agency’s requirements for intermediate equity content within its total adjusted capital, and equity credit from a global insurance rating agency A M Best, for the QIC Group.
BNP Paribas acted as sole structuring adviser on this transaction. BNP and HSBC jointly acted as global coordinators and BNP, HSBC, ENBD and NBAD acted as joint book runners and joint lead managers for the notes, whose settlement is expected to take place on March 13, 2017.
Qatar Re, which has already received a branch licence from the Monetary Authority of Singapore, had said acquiring branch status would strengthen its presence in Asia’s rapidly evolving insurance and reinsurance markets, while at the same time contributing to the expansion of the company’s global reinsurance footprint and risk diversification profile.
Qatar Re, whose short term outlook remains “cautiously optimistic”, had reported an 8% growth year-on-year in gross written premium to $1.25bn in 2016 despite sharp depreciation of the British pound.
Net earned premium grew faster at 43% to $351mn in 2016 on the back of solid expansion across its key geographical markets, lines of business and client segments, said Qatar Re, whose parent QIC had injected $200mn, taking its shareholders’ equity to $772mn.
The reinsurer has branch offices in Zurich and Dubai, representative offices in London and Singapore (which is expected to convert into branch), and a service company in Doha.
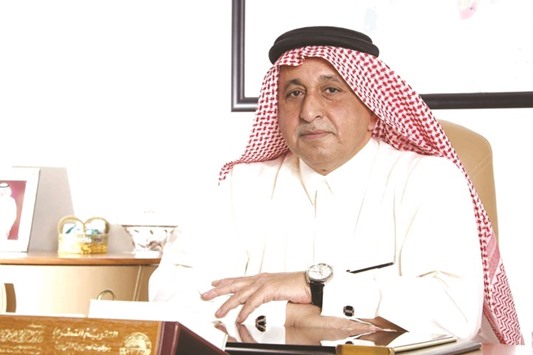
Al-Subaey: Well-positioned for next phase of growth.