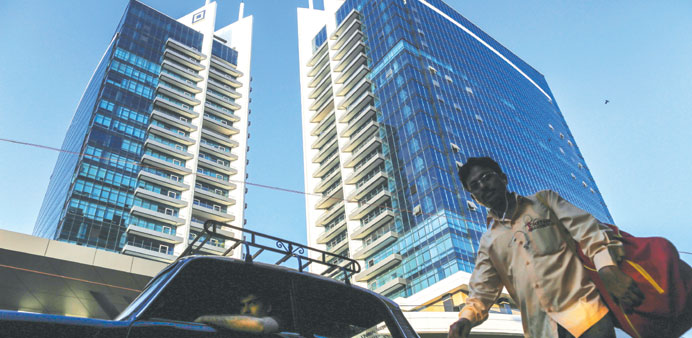
A man walks past the Peninsula Corporate Park in Mumbai. Demand for homes and loans has been stoked in India by a persisting housing shortage.
Reuters/Mumbai
Indian mortgage lender Housing Development Finance Corp (HDFC), loved by global investors for its steady profit growth, faces an intensifying battle for business and market share as banks aggressively push home loans.
With India’s economic flu hitting corporate lending, banks have cranked up efforts to tap into the country’s housing loan demand, which has proven to be brick-hard by comparison.
Demand for homes, and loans, has been stoked by a persisting housing shortage as long-term demographic changes – urbanisation, rising incomes, more nuclear families – transform how and where people live in Asia’s third-biggest economy.
With their eyes on the prize, banks such as state-run Bank of India (BoI) and ICICI Bank, the biggest private sector lender, are swarming the market with discounts and special offers, willing to even live with narrower margins. They are also expanding into lower-tier cities, a market that HDFC is nurturing.
“This is a very safe business. All our branches are working hard to grow home loans. We want to grow faster than the industry,” said Anil Verma, BoI’s chief financial officer.
BoI is setting up branches that only sell auto and home loans, taking five days to process a mortgage. It often takes between two weeks and a month to get a home loan approved in India.
State Bank of India (SBI), which dethroned HDFC as India’s top mortgage lender about two years ago, was charging mortgage interest of up to 200 basis points above its base rate in 2011. SBI is now offering home loans at just 10-30 bps above the base rate, underscoring the intensifying competition.
SBI’s home loans grew 20% in the September quarter from 13% a year earlier. ICICI doubled its mortgage growth to 23%, while HDFC was flat at 23%, according to a report by Ambit Capital this month.
But the battle for mortgage borrowers is threatening to squeeze net interest margins (NIMs). Analysts expect a 10-20 basis point margin decline for Indian banks in the year ending March 2014 from an average of 3.1% in 2010/11.
Brokerage Jefferies expects HDFC’s NIM to ease to 4.14% from 4.4% over the same period.
So far, HDFC’s overall profitability has remained unscathed, thanks to demand for homes in smaller cities as well as income from other businesses.
For the December quarter, net profit grew 12% to Rs12.8bn ($206.92mn), in line with estimates. Net interest margin for the nine months ended December was at 4%, compared with 4.06% a year earlier.
Chief Executive Keki Mistry said yesterday that the competitive pressure had not hurt HDFC’s market share.
“We don’t believe that there has been any change in market share numbers. One per cent up, 1% down sometimes happens on a month-to-month basis, but we have not seen any change,” Mistry told reporters after HDFC announced its results.
For its part, HDFC, which counts Blackrock Inc, the Singapore government and Aberdeen Asset Management among its investors, is spreading into smaller cities and towns and seeking more agents to find more mortgage borrowers.
It pays a fee to partners IndusInd Bank and Ratnakar Bank to bring in customers, and its share of business from the two banks and other agents has more than doubled in three years to 17% of its total loans in the September quarter.
“We have to go out, we have to keep reaching out, we have to keep up the effort of finding more and more agents, more and more partners who will source loans for us,” Mistry said in an interview last month.
HDFC is also relying increasingly on other businesses including insurance, asset management and private equity to drive profit. In the year ended March 2013, the share of profit from subsidiaries and associate companies more than doubled to 27% from 13% in 2008.
HDFC’s stock has risen more than five times over the last decade, compared with a 263% gain in the wider market.