


IANS/New Delhi
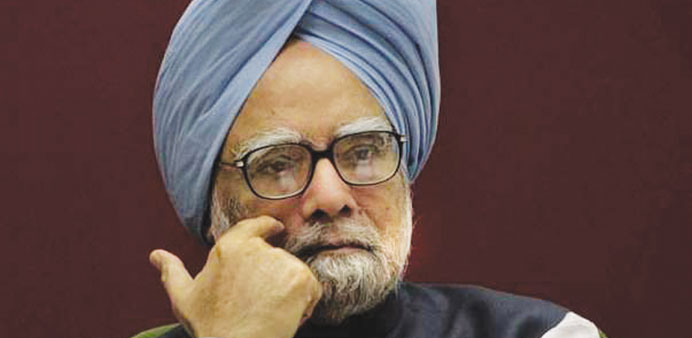
Industry leaders yesterday met Prime Minister Manmohan Singh and called for pushing up the reform process in a bid to revive growth and investments.
Reliance Industries chairman Mukesh Ambani, Infosys chairman N R Narayana Murthy, Wipro chairman Azim Premji, Bajaj Group chairman Rahul Bajaj and chiefs of leading industry chambers, among others, attended the meeting held at the prime minister’s 7 Race Course Road residence.
Finance Minister P Chidambaram, Commerce and Industry Minister Anand Sharma, Planning Commission deputy chairman Montek Singh Ahluwalia and chairman of the Prime Minister’s economic advisory council C Rangarajan were also present at the meeting.
The industry leaders asked the government to take measures to revive investments.
“Reviving investments and giving a thrust to the industrial sector should be government’s priority at the present moment,” said Federation of Indian Chambers of Commerce and Industry (FICCI) president Naina Lal Kidwai.
“A turnaround in GDP growth hinges on how the overall industrial sector performs in the months ahead. Be it fiscal policy, monetary policy or the structural reforms route, all these have to be used in tandem to lift business sentiment and create an environment where investors feel confident about their investments,” she said.
Total investments in new projects in India slumped to Rs.774bn in the April-June quarter as compared to Rs.2,226bn recorded during the corresponding quarter of last year, according to data compiled by Mumbai-based think-tank Centre for Monitoring Indian Economy (CMIE).
FDI inflows into India slumped by 38% to $22.4bn in 2012-13 as compared to $35.1bn recorded in the previous year, despite the much-touted reform measures in the areas like retail and aviation, as per the department of industrial policy and promotion (DIPP) data.
India’s economic growth slumped to a decade low of 5% in the financial year ended March 31, and the country’s current account deficit hit a record high of 4.8%. The government targets to bring it down to 4.2% in the current financial year.
The Indian rupee hit a record low of 61.21 against a dollar earlier this month.
President of Associated Chambers of Commerce and Industry (Assocham), Rana Kapoor, emphasised the need for reducing reliance on petroleum and other imports in order to control current account deficit (CAD).