


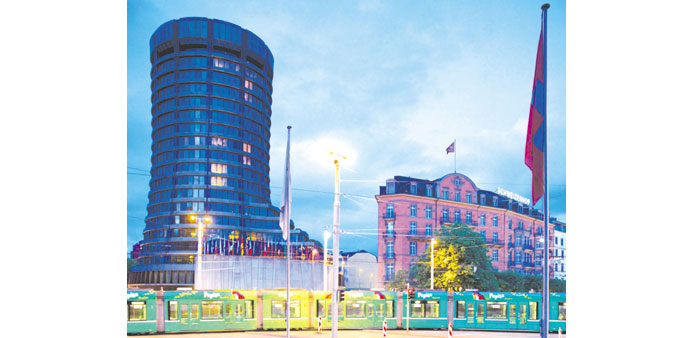
The national flag of Switzerland hangs from a flagpole near the headquarters of the Bank for International Settlements (BIS) in Basel, Switzerland on June 25. Though new rules demand that 7% of capital is set aside as a protective cushion, a bank can inflate this health benchmark by as much as 2 percentage points, depending on the risk model used, the Basel Committee on Banking Supervision, working under the BIS, said yesterday.
Reuters/London
Banks may have to hold yet more capital after a study showed wide variations in how lenders calculate risks on their books, global regulators said in their latest bid to restore trust in the tarnished sector.
Though new rules demand that 7% of capital is set aside as a protective cushion, a bank can inflate this health benchmark by as much as 2 percentage points, depending on the risk model used, the Basel Committee on Banking Supervision said yesterday.
The committee made up of regulators from top financial centres is to examine a number of options as a result of its study of 100 unnamed banks, with extra data from the world’s top 32 lenders on their sovereign, bank and corporate exposures.
“While some variation in risk weightings should be expected with internal model-based approaches, the considerable variation observed warrants further attention,” Basel Committee chairman Stefan Ingves said.
The committee put forward several policy options, with quick wins such as enhanced disclosure, extra guidance from supervisors and possible clarification of existing rules.
Over the medium term, it will examine whether to put restraints on the internal models used by banks.
Even tougher curbs could include fixed-value capital floors, which banks would have to apply even if in-house models indicate that the risk does not warrant holding as much capital.
Jamie Dimon, chief executive of US bank JPMorgan, was widely seen as attacking European rivals in 2011 when he said some lenders were lax in how they calculated risk.
The Basel study shows no clear evidence that European banks are generally more lax than US rivals, though they appear to be so in relation to their exposure to other banks.
“In the near term, information from this study on the relative positions of banks is being used by national supervisors and banks to take action to improve consistency,” said Ingves, who is also governor of Sweden’s central bank.
Basel’s review of risk weightings on trading books came up with similar variations at the start of the year and regulators have said that investors will remain cautious about the sector’s stability until they have faith in the numbers used to determine capital buffers.
“There will be more willingness to actually interfere in the risk-management processes. This means more oversight and, ultimately, for some banks it means more capital,” said Etay Katz, a lawyer at Allen & Overy.
The two studies are expected to be viewed by regulators in Britain and the US as further evidence to back their calls for speedy reform. They see the system of using risk weightings to determine capital buffers as being overly complex and are putting greater emphasis on a simpler curb on risk.
This week the Bank of England said that banks must comply with a 3% leverage ratio immediately, four and a half years ahead of the global deadline set by Basel.
The leverage ratio measures a bank’s capital against its total lending, in effect setting a straightforward cap on how much it can lend against its reserves. This measure is considered to be less easy to circumvent than risk-weighted capital ratios.
A 3% ratio means that a bank must hold capital equivalent to 3% of its loan book.
The US Federal Reserve said it will require banks to have a leverage ratio higher than Basel’s 3% minimum.
A tougher approach could raise political concerns in some eurozone countries where debt is lowly rated or where lenders are heavily exposed to each other. “I think continental European investors may be nervous - and perhaps they should be, as their risk-weighted assets are only going to harmonise one way, and that is upwards,” one UK financials fund manager said on condition of anonymity. “I don’t have much faith in the numbers used to determine capital buffers, but not because I think the banks are playing games - I am nervous because the regulators keep moving the goalposts.”
The Basel Committee may discuss what action to take when it meets in September.