


 |
|
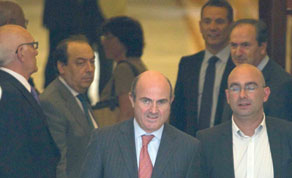
Spain’s Economy Minister Luis de Guindos carries his briefcase as he leaves parliament in Madrid, yesterday. Guindos said the government would take further measures in coming days and weeks to help bring down a debt risk premium that is seen as unsustainable. |
AFP/London
World stock markets were mixed in choppy trade yesterday with Spain’s borrowing costs rising to a euro-era record following a ratings downgrade tempered by a bout of optimism about Greek elections.
European stocks moved lower following losses in Asia, but several staged late rallies to close in positive territory including in Athens, which jumped more than 10% on hopes voters will elect a coalition Sunday that will keep it in the euro.
London’s benchmark FTSE 100 index dropped 0.31% to 5,467.05 points and in Frankfurt the Dax 30 shed 0.23% to 6,138.61 points, but in Paris the CAC 40 bucked the trend to add 0.08% to 3,032.45 points.
Milan jumped 1.47% and Madrid gained 1.22% despite the turmoil in the bonds markets.
In foreign exchange deals, the euro rose to $1.2612 from $1.2556 late Wednesday in New York. The dollar fell to ¥79.28 from 79.46.
Spain’s borrowing costs reached new dangerous highs near 7% as a bailout loan of up to 100bn euros (125bn) to salvage the nation’s stricken banks fell flat after a brief initial positive welcome.
“The rout in Spanish bonds continues relentlessly, as Madrid’s borrowing costs move ever higher and ever closer to the dangerous seven% level,” said Chris Beauchamp, a market analyst at trading group IG Index.
Meanwhile, Greek shares soared more than 10% on speculation that voters will elect a government committed the austerity policies key to it receiving further bailout aid and staying in the euro.
Analysts at IG markets said most investors were staying on the sidelines until after the Greeks vote, leading to higher volatility.
“Investors were nevertheless a little more optimistic than at the beginning of the session in a market fuelled on rumours hopeful that a pro-austerity government will be elected,” they added.
The interest rate on Spanish 10-year government bonds soared to just under 7.0% to their highest since the birth of the single currency and were up sharply from 6.721% Wednesday.
Neil MacKinnon, an economist at financial group VTB Capital, said that a level of 7.0% was “considered by the markets to be a tipping point which eventually increases the prospect of a government bailout.”
Italy also had to pay investors much higher rates of return yesterday, reflecting increasing concerns over the eurozone debt crisis, when it raised medium- and longer-term financing.
Such high rates are regarded by many analysts as impossible for Spain to afford to finance its activities over the longer term, raising the risk of a bigger bailout, as was the case for Greece, Ireland and Portugal.
Moody’s Investors Service slashed Spain’s sovereign debt rating by three notches late Wednesday to Baa3 and left it on review for a possible further downgrade.
Since many institutional investors are barred from buying bonds that are rated as junk, or non-investment grade, the prospect of a further downgrade sent a further chill through the market.
The borrowing “will materially worsen the government’s debt position,” Moody’s said, projecting the country’s public debt ratio to hit 90% of gross domestic product output this year and to continue rising through 2015.
US stocks climbed higher despite disappointing government economic data on jobs and inflation.
In midday trade, the Dow Jones Industrial Average was up 0.85% to 12,603.09 points.
The S&P 500-stock index advanced 0.78% to 1,325.08 points, while the tech-heavy Nasdaq Composite climbed 0.61% to 2,820.63.
Weekly initial jobless claims rose more than expected and consumer prices fell in May for the first time in two years, driven by falling gasoline prices, but core inflation rose 0.2% for the third straight month.