Reuters/Madrid
Spaniards alarmed by the dire state of their banks are squirreling money abroad at the fastest rate since records began, figures showed yesterday, and the credit ratings of eight regions were cut.

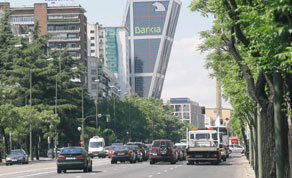
Bankia headquarters building is seen in Madrid. Spain must lay out its restructuring plans for Bankia to the European Commission, a spokesman for the EU executive arm said yesterday. He added that a domestic solution to the country’s bank crisis would be better than a European rescue
Spain is the next country in the firing line of the eurozone’s debt crisis, with spendthrift regions and shaky banks threatening to blow a hole in state finances and pushing funding costs towards levels that signal the need for a bailout.
The European Commission gave new help on Wednesday, offering direct aid from a eurozone rescue fund to recapitalise Spanish banks and more time for Madrid to reduce its budget deficit.
That helped lower the risk premium investors demand to hold Spanish 10-year debt rather than the German benchmark yesterday, but it remained close to the euro-era record, at 520 basis points.
Bank of Spain data showed a net €66.2bn ($82.0bn) was sent abroad last month, the most since records began in 1990. The figure compares to a €5.4bn net entry of funds during the same month one year ago.
Spaniards are worried about the health of their banks, hit by their exposure to a 2008 property crash, and have been sending money to deposit accounts in stronger economies of northern Europe.
The capital flight data predates the nationalisation of Spain’s fourth biggest lender Bankia in May when it became clear the bank could not handle losses from bad real estate investments, compounded by a recession.
Spain’s centre-right government has contracted independent auditors to assess the health of its financial system in an effort to restore faith in its banks.
Spain must lay out its restructuring plans for Bankia to the European Commission (EC), a spokesman for the EU executive arm said yesterday. He added that a domestic solution to the country’s bank crisis would be better than a European rescue.
The government said on Wednesday it would finance a €23.5bn rescue of the bank through the bank fund, FROB but senior debt bankers said that the syndicated bond market is currently closed for Spanish agencies.
The prospect that Spain might not be able to handle losses at its banks has pummelled shares and the euro, although both regained some stability yesterday.
“What we need first of all is for the Spanish government to tell us its restructuring plans for Bankia, what options it is considering,” said European Commission spokesman Amadeu Altafaj in a radio interview.
“From there, we will study the plans and see whether they comply with requirements for public aid.”
Spain should carry out the refinancing of its banking sector, laid low by a decade of unsustainable lending during a property boom, by market mechanisms or government funds, rather than a European rescue which would have negative connotations, Altafaj said.
“The sooner uncertainties are removed the better,” he added.
The government also hopes to clear doubts today about how it plans to ease financing problems among its 17 autonomous regions.
Treasury ministry sources said a mechanism to back the regions’ debt would be agreed at the weekly’s cabinet meeting and figures showing they were on track to meet their spending cuts targets would be released.
Fitch Ratings downgraded eight regions yesterday, warning that a failure from the government to adopt new measures would result in further ratings cuts.
Spain’s Deputy Prime Minister Soraya Saenz de Santamaria was due to meet US Treasury Secretary Timothy Geithner and International Monetary Fund Director General Christine Lagarde in Washington yesterday.