


Reuters/Washington
The number of Americans submitting new applications for jobless benefits edged down last week, easing concerns the labour market was deteriorating after surprisingly weak employment growth in April.

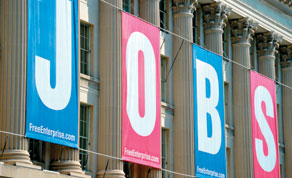
A jobs sign is seen on the front of the US Chamber of Commerce building in Washington, DC (file). New claims for state unemployment benefits slipped 1,000 last week to a seasonally adjusted 367,000, the Labour Department said yesterday
Another report yesterday showed the US trade deficit widened in March, with exports surging to a record high and a rise in imports highlighting the economy’s firming underlying demand.
Together, the reports indicated the economy remains on a moderate growth path, despite the softer jobs growth and signs the service sector slowed in April.
“The slowdown we have seen in economic activity and employment growth during in the past two months may be in the rear view mirror,” said Millan Mulraine, senior macro strategist at TD Securities in New York.
New claims for state unemployment benefits slipped 1,000 last week to a seasonally adjusted 367,000, the Labour Department said. Economists who had expected claims to rise to 369,000 said the decline suggested seasonal distortions that had led to a spike in applications last month was probably over.
The four-week moving average for new claims, considered a better measure of labour market trends, fell 5,250 to 379,000.
Separately, the trade gap widened 14.1% to $51.8bn in March, the biggest jump in nearly a year, as a surge in imports swamped a rise in exports, which hit a record high.
Imports grew 5.2%, the biggest gain since January. That jump was consistent with a rise in consumer spending seen during the first quarter.
Exports had another good month, rising 2.9%, suggesting the global economy had not slowed as much as people had feared.
While a widening trade deficit is a drag on gross domestic product, the details of the trade report were broadly in line with the government’s assumptions when it made its first GDP estimate last month.
Still, the government’s gauge of first-quarter GDP growth is expected to be lowered to an annual pace of about 1.9% from 2.2% because of a smaller-than-expected rise in wholesale inventories in March report on Wednesday.
The claims data and bargain-hunting helped to lift US stocks in early morning trade. US Treasury debt prices fell, while the dollar was little changed against a basket of currencies.
Coming on the heels of April’s sluggish employment gains, the claims data calmed fears the labour market was stagnating. Companies added a meagre 115,000 new jobs to their payrolls in April, the fewest in six months, the government said on Friday.
Most economists have viewed the pull-back in job creation as payback for stronger activity during the unusually warm winter and believe the underlying pace of payrolls growth is around 175,000 a month - its average for the past three months.
Scott Brown, chief economist at Raymond James in St Petersburg, Florida said the jobless claims figures had “simmered down after the noises we had earlier.” “This shows we have moderate job growth. They’re consistent with monthly job payroll growing at 150,000 to 180,000,” he said.
‘Even worthy borrowers can’t get mortgages’
Banks have become so restrictive in making mortgages that many worthy homebuyers are being frozen out of the US housing market, and lending practices are not likely to loosen any time soon, Federal Reserve Chairman Ben Bernanke said yesterday.
Speaking via satellite to a banking conference in Chicago, Bernanke highlighted ongoing problems in mortgage finance availability, even though banks are much healthier now as the 2007-2009 financial crisis has receded.
“To be sure, a return to pre-crisis lending standards wouldn’t be appropriate,” Bernanke said. “However, current standards may be limiting or preventing lending to many creditworthy borrowers.”
Lax lending practices, including “liars’ loans” handed out to borrowers who provided little or no documentation for jobs and incomes, have been cited as a key contributing factor in precipitating the severe financial crisis.
Bernanke implied the backlash by banks against criticism of their lending practices, which now are far tighter, might be overdone and will be extremely hard to reverse.
“Many factors suggest this situation will be difficult to turn around quickly, including the slow recovery of the economy and housing market, continued uncertainty surrounding the future of the government-sponsored enterprises, the lack of a healthy private-label securitisation market, and cautious attitudes by lenders,” Bernanke said.