


London/AFP
US stocks rebounded and European shares rallied in a highly volatile trading session yesterday marked by concerns over banks and an announcement of a meeting of French and German leaders on the eurozone crisis.

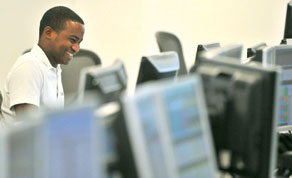
A dealer smiles on the trading floor of IG Index in the City of London, yesterday. World shares were higher yesterday as strong US jobs data took some of the focus away from renewed fears about the health of the eurozone banking system
In London, the FTSE 100 index climbed 3.11% to finish at 5,162.83 points, while in Frankfurt the Dax climbed 3.28% to 5,797.66 points and in Paris the CAC 40 rose 2.89% to 3,089.66 points.
Over on Wall Street, in midday trading, the Dow Jones Industrial Average was up 2.50% to 10,988.12, after losing 520 points on Wednesday.
The broader S&P 500 gained 2.58% to 1,149.64, while the tech-heavy Nasdaq surged 2.90% to 2,450.04.
Asian stock markets mostly fell yesterday but closed off their early lows as some traders went bargain-hunting despite Wednesday’s huge falls in Europe and on Wall Street.
On the forex markets, the euro rose to $1.4245 in late European trade from $1.4178 on Wednesday.
The dollar finished at ¥76.74, down from 76.90 in New York on Wednesday.
Gold prices pulled back to $1,760 per ounce, after hitting a fresh record high of $1,814.95 overnight as investors sought the safe-haven precious metal.
After volatile trading during the day stocks in Europe moved up in the afternoon after French President Nicolas Sarkozy called a eurozone crisis meeting with his German counterpart.
Merkel will travel next Tuesday to Paris for the meeting aimed at producing “joint proposals” by September on how to better manage the euro and avoid future instability, Sarkozy’s office said.
Financial markets have suffered dizzying losses in recent days and weeks amid mounting concern that the eurozone debt crisis and weak US economy could help push the world back into recession.
Markets were also haunted by the downgrade of the US credit rating last week, with investors anxious to anticipate the next top-notch country to lose its triple-A rating.
Elsewhere in Europe, Milan rallied by 4.1%, Madrid by 3.56%, and Lisbon by 1.72%. Brussels rallied by 2.54%, Amsterdam by 1.99%, and Zurich jumped by 5.02%.
IG Markets analyst Soledad Pellon Bannatyne said it was too early to say the market has turned a corner.
“We cannot say the market has turned around. We have seen everything during the day,” she said.
“There is no concrete reason” for Thursday’s rally. “We consider it to be a technical rebound,” she added.
During the day rumours persisted on the stability of French banks amid renewed concern over exposure to troubled Greek debt.
Societe Generale aggressively pushed back against talk of its imminent demise, with the French financial regulator warning anyone profiting on “false information” would face penalties.
It also emerged European banks were increasingly turning to the European Central Bank overnight lending facility instead of borrowing from one another, suggesting suspicions of poor bank liquidity remain. European interbank lending rates were also on the rise.
“Markets will continue this giddying roller-coaster of fear until there is any indication that European policymakers are starting to set the agenda and not reacting to it. Think we have a lot more of this in the coming days and weeks,” Michael Hewson, Market Analyst at CMC Markets said.
Italy promised yesterday to meet many of the demands made by European Central Bank for major economic reforms in return for help in shielding the country from the debt crisis.
“We need to have very strong austerity measures in 2012 and 2013,” Finance Minister Giulio Tremonti told lawmakers, who had been called back from summer holidays to debate the moves.