AFP, Reuters/London
Surprisingly robust US jobs data sparked only a brief rebound on Wall Street and in Europe yesterday, leaving investors scarred from a week of heavy losses brought on by slow growth and eurozone debt concerns.

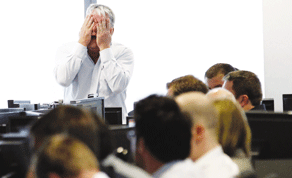
A broker reacts at BGC Partners at Canary Wharf financial district in London, yesterday. Banks and commodity stocks fell sharply yesterday as Britain’s top share index extended losses into a sixth straight trading day
European stock markets initially dived 3-4% before rallying quickly, following the announcement that the US economy gained a net 117,000 jobs in July.
London’s FTSE-100 index closed down 2.71% to 5,246.99 points for a weekly loss of 9.8%, wiping nearly £150bn ($246bn) off its total value over the last five days.
In Frankfurt, the Dax dropped 2.78% to 6,236.16 points, dropping 13.3% over the week.
In Paris, the CAC-40 slid 1.26% to 3,278.56 points to chalk up a record 10th consecutive daily loss. It lost 10.7% over the week.
In highly volatile trading, Madrid and Milan rebounded for part of the day on rumours that that the European Central Bank was preparing to buy hard-hit Spanish and Italian bonds, before falling back.
Madrid ended the day down 0.18% and dropped 10% over the week, while Milan fell 0.7% and lost 13.12% for the week.
Wall Street also opened higher on the surprisingly strong jobs data, but the rally quickly fizzled.
The Dow Jones Industrial Average had dropped 1.9% to 11,168.17 points at 1600 GMT, and was down 8.03% from the previous week’s close.
The broader S&P 500 was down 2.5% to 1,198.67 points, while the tech-heavy Nasdaq Composite slumped 3.4% to stand at 2,470.17 points.
“The reality of a global economic contraction seems to have finally kicked in as the markets continue to plummet,” said Manoj Ladwa, senior trader at ETX Capital in London.
“Investors are pricing in a slowdown in growth and sovereign debt problems as equities drop across the board,” he added.
China said that debt-reduction announcements in Europe and the US, where the permitted ceiling was again raised, would not be enough to save their respective economies.
“Concrete steps” must be taken to rebalance the global economy, said a commentary published by the official Xinhua news agency.
“We’re seeing the erosion and now the loss of confidence, confidence in the economy, confidence in the market, confidence in the policy makers. It’s all showing up,” said US-based Hugh Johnson, of Hugh Johnson Advisors.
The latest front cover of the Economist publication meanwhile carried the headline: ‘Time for a double dip?’ – with the respected magazine questioning whether the US will fall back into recession.
A double-dip recession refers to a short-lived recovery from one recession and then a new plunge back into economic contraction.
“While we are not looking for a global recession, which is a surprisingly rare event, there is a lot of confusion out there,” said Kathleen Brooks, an analyst at Forex.com traders.
“The markets staged impressive rallies over the last two years on the basis that global growth would bounce back. However, the recovery has been shallower than expected and now the markets have to re-adjust.
In the foreign exchange market, the euro rose slightly to buy $1.4157 at 1600 GMT from $1.4106 late on Thursday. The euro earlier rose as high as $1.42470.
The dollar also slid against the yen, buying ¥78.48 against 78.93 late on Thursday.
The franc rose to a record high against the euro of 1.0710 francs in early Asian trade but retreated to 1.0904 in New York dealing.